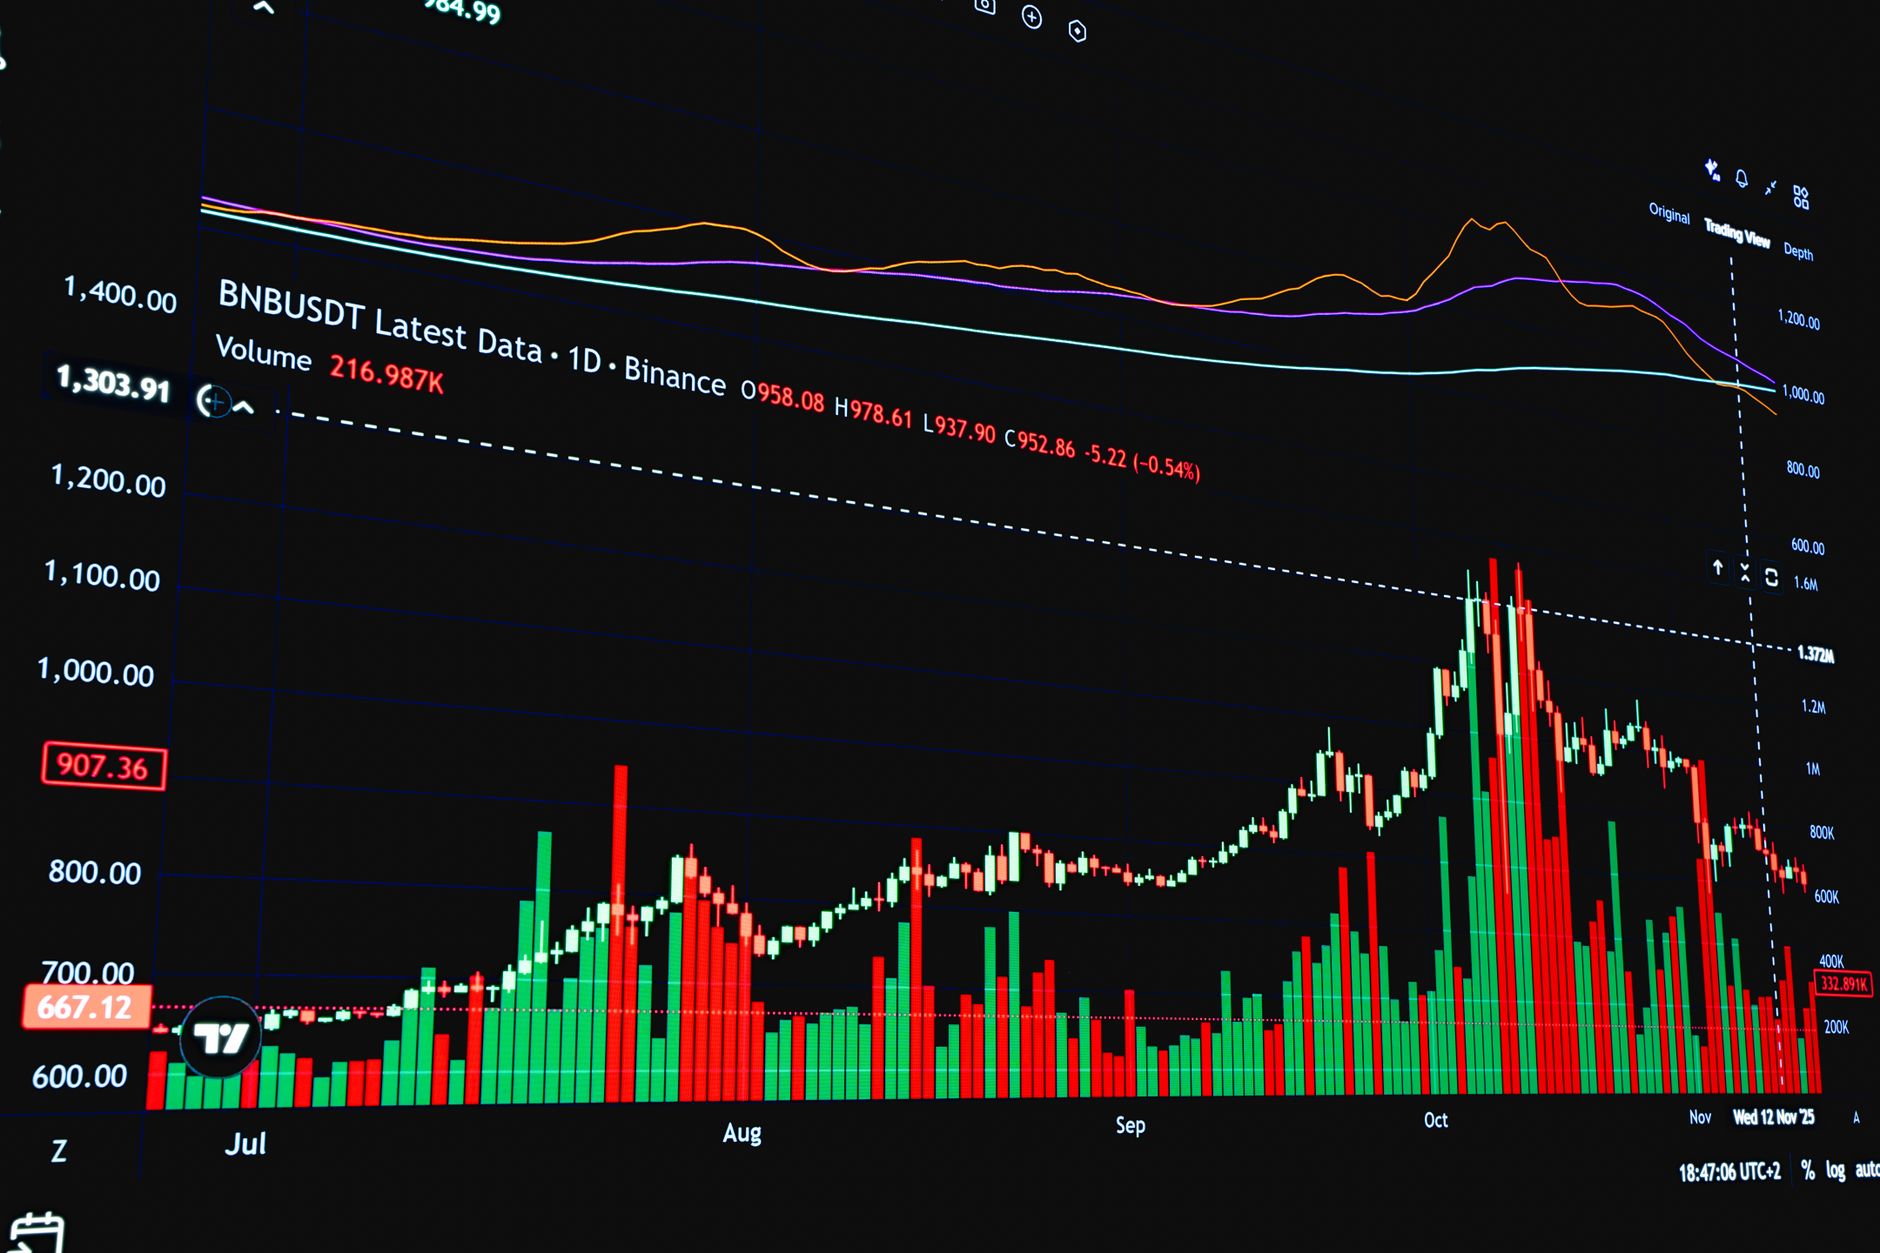
Bitcoin’s share of total crypto market capitalization crossed 65% in early September 2026, a level not seen since early 2021. That number tends to get treated as a cycle indicator - dominance rises in bear markets, falls when altcoins run - but the current setup doesn’t map cleanly onto that pattern. The broader market isn’t in distress. Bitcoin itself is trading well above its 200-day moving average. This is dominance expanding during a bull phase, which is a different animal.
The on-chain explanation is fairly straightforward. Spot Bitcoin ETF flows, which have been net positive for most of 2026, are pulling institutional dollars into BTC specifically - not into the asset class broadly. That capital doesn’t rotate down the risk curve. A pension allocation or a sovereign wealth fund adding Bitcoin exposure isn’t going to subsequently rebalance into mid-cap layer-1 tokens. The demand profile has changed structurally, and altcoin markets are priced as if the old rotation playbook still applies.
Look at ETH/BTC. The ratio has continued grinding lower through Q3 2026, sitting near levels that would have been considered capitulation territory in 2022. Ethereum’s network activity is real - fee revenue has recovered since the Pectra upgrade, and DeFi TVL in dollar terms is up - but that’s not translating into price outperformance against Bitcoin. The market is separating “functional” from “investable” in ways that hurt ETH’s narrative as a catch-up trade.
The Liquidity Argument
Institutional positioning explains part of this, but there’s also a liquidity argument that’s less discussed. Altcoin markets are thinner than they appear. During the last broad altcoin rally in late 2024, a significant portion of volume was concentrated in a small number of tokens - many of which have since lost 60–80% of their peak valuations. That kind of drawdown history makes risk-adjusted rotations unattractive to anyone managing serious capital.
Bitcoin dominance at 65% isn’t a sign the market is broken. It’s a sign the market is maturing in a specific direction - toward a Bitcoin-as-reserve-asset structure where everything else is a satellite trade. That might eventually change, but the on-chain flows and institutional allocation patterns right now aren’t pointing toward a reversal in the next quarter.